
The expense account uses its debit balance to reduce the revenue account’s credit balance. In the realm of accounts receivable, the allowance for doubtful accounts, also known as the bad debt reserve, is a critical contra asset account. It represents an estimate of the portion of a company’s receivables that may not be collectible.
What is a Contra Account? Definition
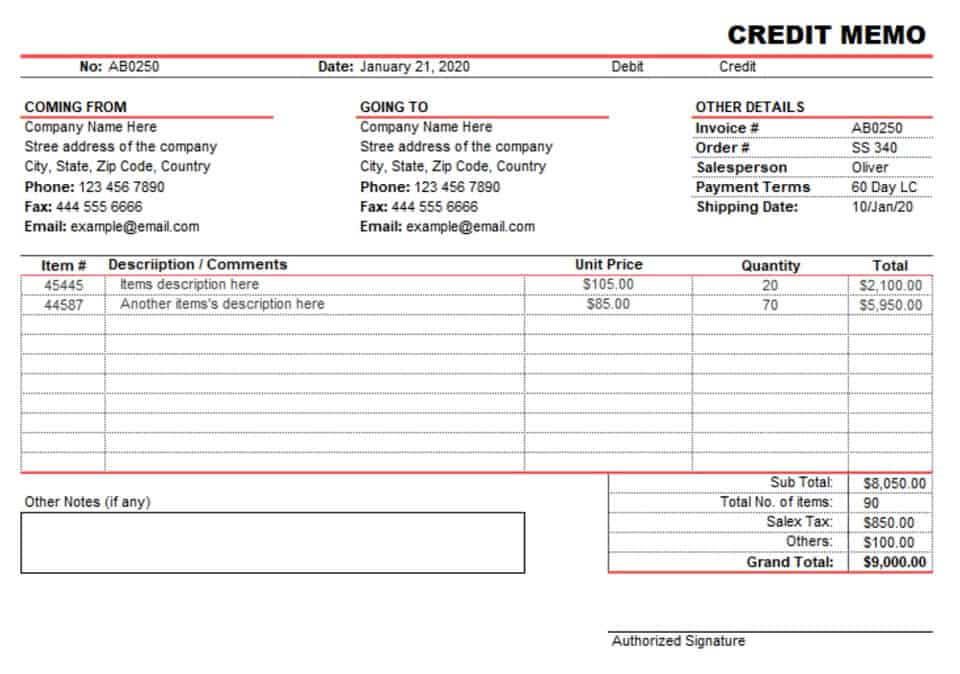
- The revenue contra accounts Sales Returns, Discounts and Allowances are subtracted from the main Sales Revenue account to present the net balance on a company’s income statement.
- Similarly, allowance for doubtful accounts lowers total accounts receivable, indicating the realistic cash inflow expected from customers.
- In fact, as the name “contra” suggests, it is the opposite of aspecific class of account.
- It plays a vital role in maintaining the accuracy and transparency of a company’s financial statements.
- Sales returns and allowances adjust gross sales to reflect net sales, which is essential for businesses with significant returns or discounts.
- By reflecting both accounts on the balance sheet, analysts can understand both the original price and the total decrease in value of a certain asset over time.
Contra asset accounts also provide a clear picture of the companies’ accumulation of assets. Allowance for receivables is an account that companies maintain to record possible bad debts. This account offsets the balance in the respective asset account that they pair with on the balance sheet. A contra account is an account that companies use to reduce the value of a related account. It usually nets off against related accounts and provides an opposite effect to the balance.
What is a Contra Asset Account? Definition, Types, Example, and More
By properly managing depletion accounting, companies in these industries can better track and allocate the costs and value of their natural resources. This also ensures accurate financial statements, which is essential for meeting regulatory requirements and maintaining the trust of stakeholders. Contra equity accounts, those intriguing components in the equity section of the balance sheet, reflect transactions that reduce the total equity available to shareholders. The most common one you might encounter is treasury stock—where companies buy back their own shares. It’s essentially a reverse investment; instead recording transactions of pouring money in, the company is taking it back, reflecting a decrease in shareholders’ equity. This can have various strategic implications, from attempting to increase per-share earnings to trying to prevent takeovers.
Understanding Contra Asset Account Types and Examples
This account is essential for accurate financial reporting, as it acknowledges the potential risk of non-payment by customers. For instance, when a company buys back their own shares, they register them in a ‘Treasury Stock’ contra equity account, which reduces total shareholders’ equity. If a customer returns a product, the ‘Sales Returns’ contra revenue account lowers the total sales revenue, reflecting the true income. Contra asset examples like ‘Accumulated Depreciation’ reduce the value of fixed assets, showing their worth after usage over time. A contra account is an account that reduces the balance of a related account.
After one year, the Equipment account shows $40,000 ($50,000 – $10,000), and Accumulated Depreciation shows $10,000. Each of these contra accounts serves to provide more detailed information about the transaction history of the related main account. By tracking contra accounts, a company can make more informed decisions about asset management, liability settlement, and overall financial planning.
For example, the allowance for doubtful accounts impacts accounts receivable turnover, while accumulated examples of contra assets depreciation affects return on assets. These adjustments ensure that financial ratios accurately reflect a company’s performance. This contra account ensures that the inventory value presented on the balance sheet is not overstated. Examples include accumulated depreciation, sales returns and allowances, and contra equity accounts like treasury stock. Equity recorded as a debit balance is used to decrease the balance of a standard equity account.
1. Sales Discounts, Returns and Allowances Revenue Contra
This article will give you the definition of contra in accounting, talk about different contra accounts, and give examples. These examples highlight how accumulated depreciation impacts both asset valuation and overall financial reporting accuracy. A contra expense account is an account used to reduce the amount of an expense without changing the balance in the main expense account.
- For instance, if a company has $100,000 in accounts receivable and expects 5% to be uncollectible, it records $5,000 in ADA to offset the accounts receivable balance.
- Their management requires precise bookkeeping practices to ensure financial statements reflect an entity’s true financial position.
- Get instant access to video lessons taught by experienced investment bankers.
- For example, a grocery store displays advertisements for a national brand in its weekly flyer.
- Still, it is important when possible to consider how the net accounts are calculated and be wary of companies that are reporting a ton of bad debts.
The equity section of the balance sheet is where the shareholder’s claims to assets are reported. The main contra equity account is Accounts Payable Management treasury stock, which is the balance of all stock repurchased by the company. When a company repurchases shares, it increases the fractional ownership of all remaining shareholders.
Why Contra Asset Accounts Matter in Accounting
By adjusting the value of inventory on hand, a company can present a financial position that closely matches the inventory’s market value. Accumulated depreciation tracks the decline in the value of fixed assets over time. To guarantee that the financial accounts show an accurate net asset value, a portion of the asset’s worth is subtracted annually to account for wear and tear. The main advantage of using a contra asset account is to separate this reduction from the asset account with which it is paired.